
BTC Market Pulse: Week 11

Overview
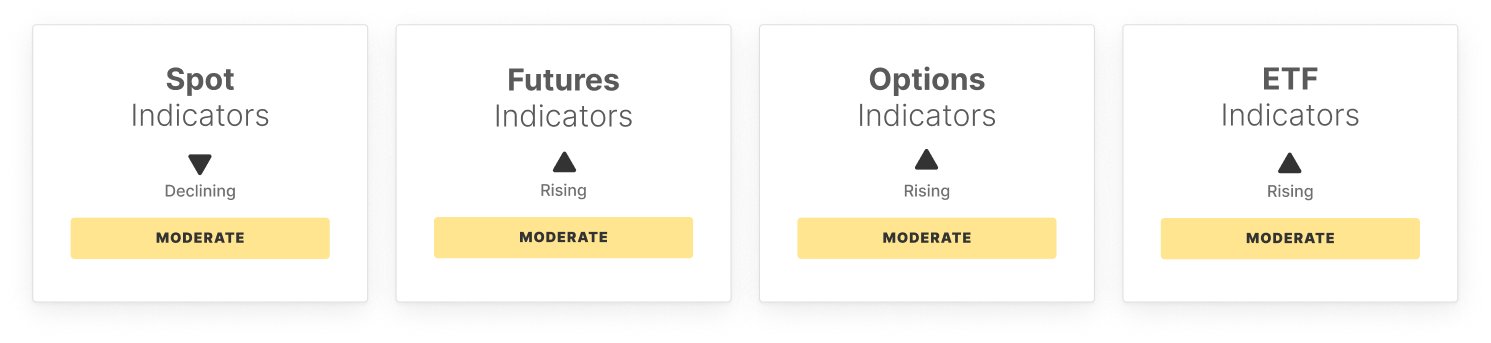
Bitcoin pulled back from $74k, while internals showed tentative signs of improvement. Momentum has firmed modestly, with RSI lifting from recent lows, but price action still lacks the strength of a decisive bullish shift. Spot activity remains subdued, with lower trading volume pointing to softer participation even as conditions begin to stabilize.
Derivatives positioning is mixed. Futures open interest increased, signalling modest leverage build-up, while long-side funding turned sharply negative, reflecting stronger demand for short exposure. Perpetual CVD rose aggressively, suggesting buy-side activity is returning in leveraged markets, though conviction remains limited.
Options markets have become less defensive. The volatility spread narrowed meaningfully as implied volatility moves closer to realised conditions, while 25-delta skew declined, pointing to softer demand for downside hedging and a more balanced near-term backdrop.
ETF activity remains a relative area of strength. Net inflows accelerated and trading volumes picked up, highlighting continued traditional finance engagement. However, the ETF MVRV ratio fell sharply into negative territory, showing the average ETF holder is now underwater and positioning stress remains elevated.
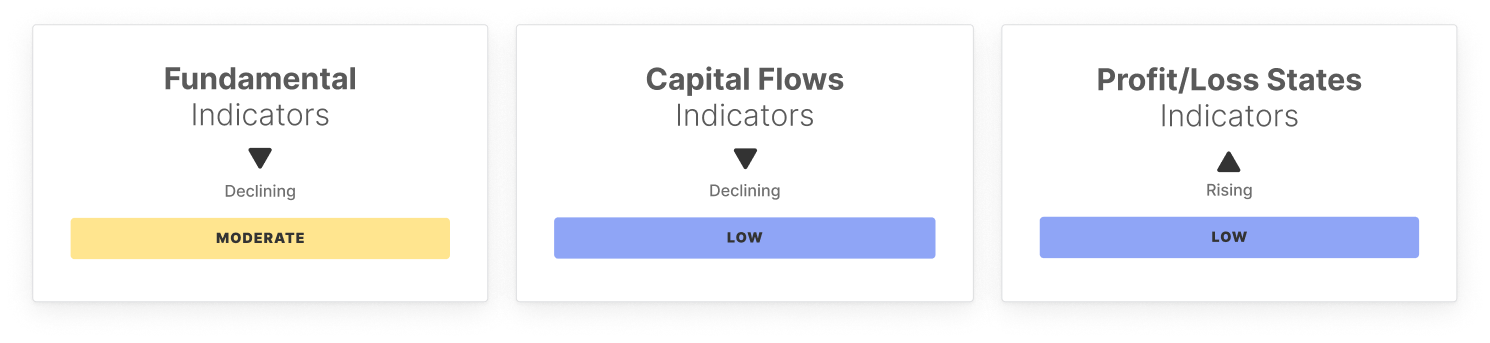
On-chain signals are mixed but slightly constructive. Transfer volume improved, pointing to firmer capital movement, while active addresses and fee volume remain soft, consistent with a quieter network backdrop. Realized cap change is still negative, though outflows are easing slightly, suggesting capital pressure may be starting to stabilize.
Positioning and profitability metrics still reflect a fragile but improving structure. The STH/LTH supply ratio remains elevated, showing short-term participation is still high, while hot capital share stays suppressed, signalling limited speculative churn. Meanwhile, supply in profit, NUPL, and the realized profit-to-loss ratio all improved modestly, suggesting market stress is easing.
Overall, conditions are stabilizing, with momentum, ETF demand, and profitability metrics improving modestly. However, capital flows remain soft, speculative participation is limited, and broader conviction has yet to fully return.
Off-Chain Indicators
On-Chain Indicators
Don't miss it!
Smart market intelligence, straight to your inbox.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Midterm elections expose market vulnerability! AI trading faces rigorous scrutiny, U.S. stock earnings expectations may undergo major adjustments
The results of the US midterm elections and the subsequent market crash have exposed the vulnerability caused by the market’s excessive concentration of bets on artificial intelligence (AI). Investors may need to readjust their expectations for investment returns.

SpaceX unlock wave meets index rebalancing! Goldman Sachs estimates: December rebalancing may bring $10.9 billion in passive buying
The proportion of SpaceX's freely tradable shares has increased from about 5% at the time of its IPO to one-third, and the expansion of index weightings is driving passive funds to increase their holdings. According to Goldman Sachs, the rebalancing of the Russell 1000 Growth Index on December 11 may trigger $10.9 billion in buy orders, with the main counterparts being insiders whose shares are unlocked. The S&P 500 inclusion window points to the second half of 2027, when the competition among passive funds will further intensify.
Citigroup Q3 Holdings: Nvidia (NVDA.US) Remains Top Heavy Position, Expanded Both Index and Tech Stock Options
According to the disclosure by the U.S. Securities and Exchange Commission (SEC), Citigroup (C.US) submitted its third quarter holdings report (13F) as of September 30, 2026, on November 4, 2026.

Carlyle still favors the healthcare sector in Q3, with Medline (MDLN.US) and StandardAero (SARO.US) accounting for over 98% of holdings
Carlyle (CG.US) has submitted its third-quarter holdings report (13F) for the period ending September 30, 2026.

Crypto prices
More


