A Rare 70-Year Warning Flashes in U.S. Stocks: QMJ Factor Surges 14.3% in a Single Month, a Pattern Seen Before Two Major Bear Markets
As a CFD analyst who has long tracked U.S. equities and derivatives markets, I have to say that the U.S. stock market is currently flashing a warning signal that is extremely rare and cannot be ignored. This signal does not appear often, but whenever it does, it is almost always accompanied by a sharp shift in market style.
1. An Abnormal Reading Seen Only Once in 70 Years
The Quality Minus Junk factor (QMJ), which measures the relative performance of high-quality stocks versus low-quality stocks, surged 14.3% in July this year, marking the largest one-month gain since records began in 1957. Historically, the second- and third-largest monthly gains occurred in November 2000 and October 2008, respectively—exactly during the two major bear markets of the dot-com bubble and the financial crisis. Now that the indicator has surged again, market caution has naturally increased.
2. What Exactly Does QMJ Measure?
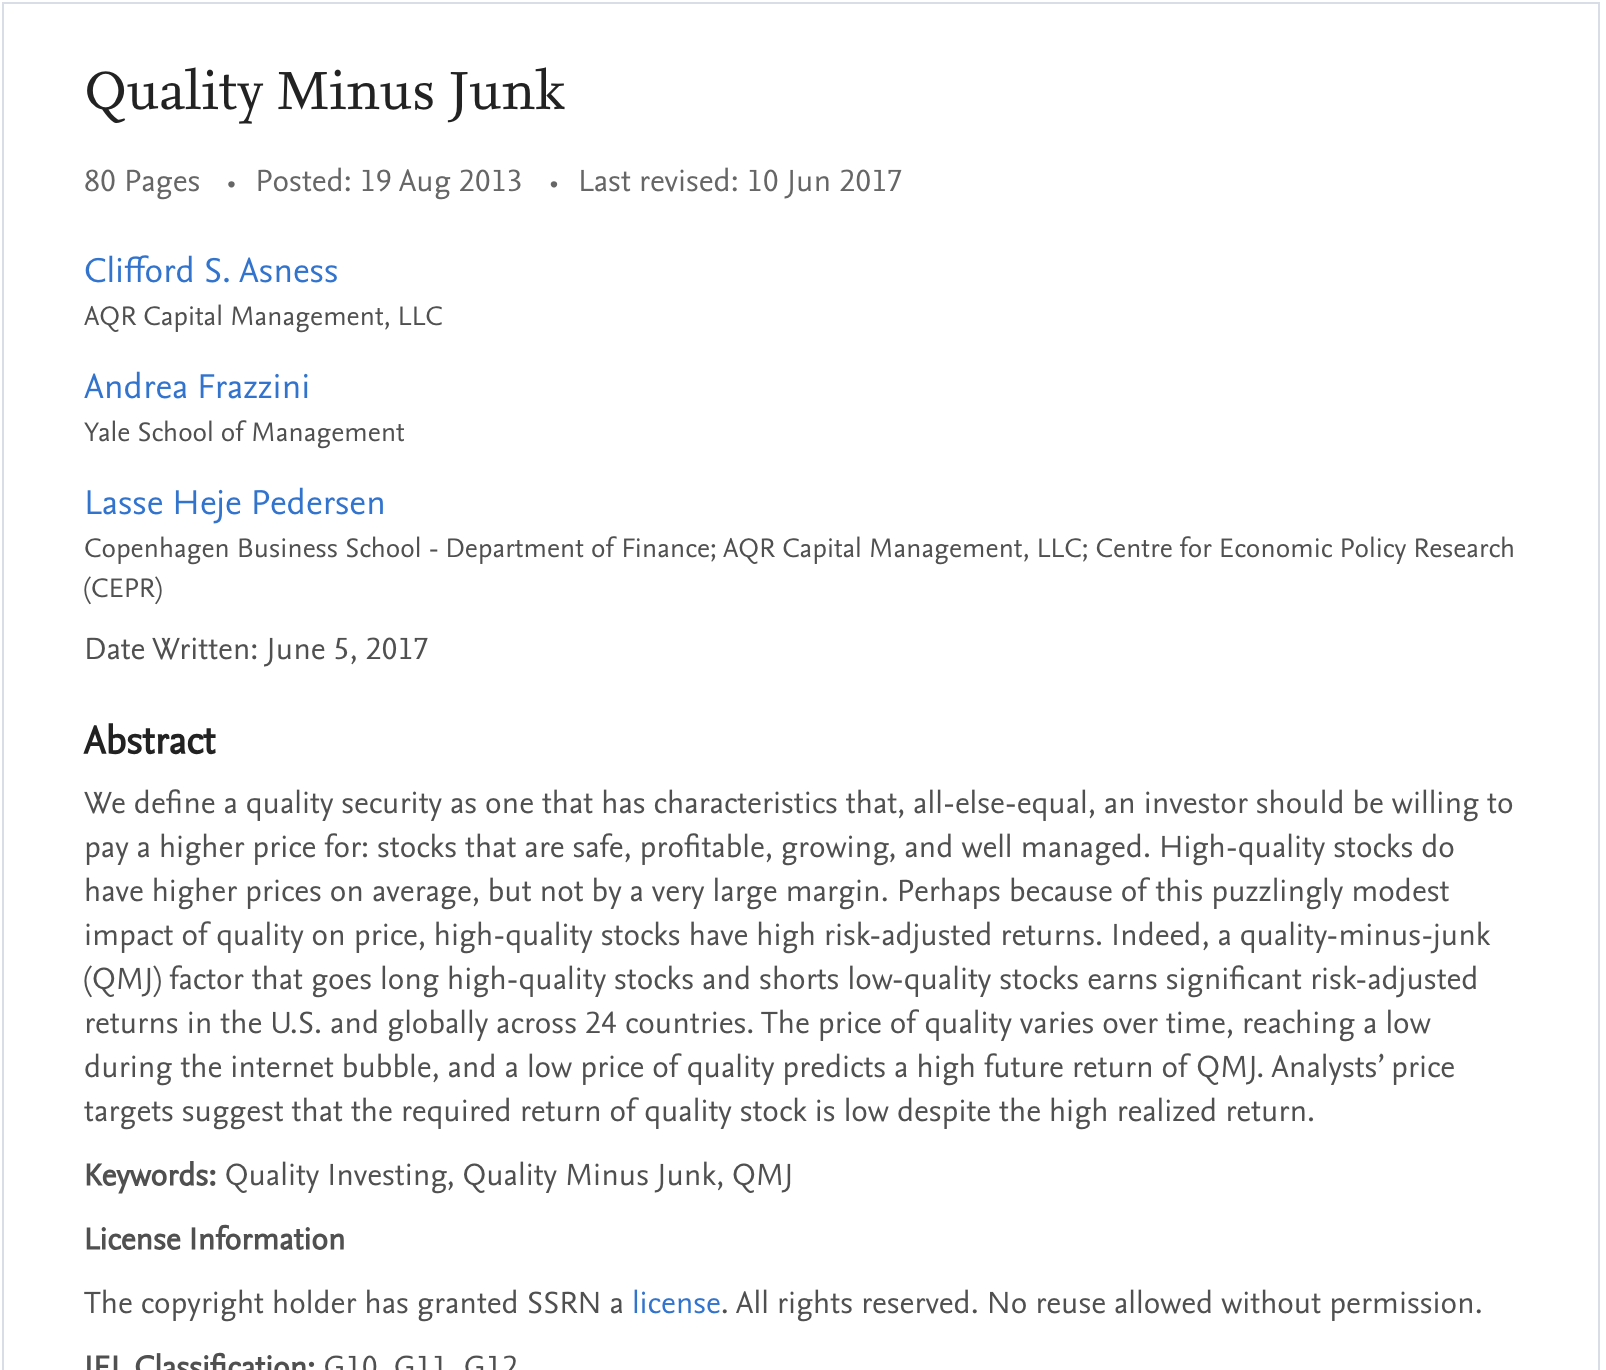
QMJ was proposed in 2013 by Cliff Asness, founder of AQR Capital Management, and his colleagues. U.S. market data can be traced back to July 1957. Each month, it scores U.S.-listed stocks, buys the top 30% by quality, and shorts the bottom 30%, using market-cap weighting and monthly rebalancing.
Quality is measured across three major dimensions: profitability (six indicators), growth (change in EPS over the past five years), and safety (stock price volatility, balance-sheet soundness, and ROE volatility). The key point is that QMJ completely ignores valuation and measures only corporate quality. A rising indicator means high-quality stocks are relatively outperforming; it does not mean the overall market is rising.
3. The Turning Point After the Strongest Leadership Rally of Low-Quality Stocks in History
The background to this warning is that low-quality stocks have experienced the longest and most powerful leadership rally in history. From November 2023 through June 2026, a portfolio long the highest-quality companies and short the lowest-quality companies lost 36% cumulatively—the worst performance for QMJ since 1957.
The driver was AI mania. Bloomberg data show that the loss-making tech basket tracked by Goldman Sachs surged 57% in the first five months of this year, far exceeding the S&P 500's 11% gain over the same period. The Russell 2000 small-cap index, more than a quarter of whose constituents are loss-making, also rose 22.7% in the first half, more than twice the gain of the broader market. The current stock market is a “tech-driven junk-stock bubble” whose scale is the largest on record, and the view is that “now is a time for caution.”
4. What History Tells Us
Since 1957, QMJ has experienced eight down cycles with declines exceeding 10%. Typical cases driven by tech mania include the electronics and computer boom of the 1960s, the dot-com bubble of 1999, and the 2020 boom in electric vehicles, cryptocurrencies, and remote work.
Within two years after these three bubbles burst, high-quality stocks outperformed low-quality stocks by 28%, 68%, and 41%, respectively. In other words, when speculative mania cools, capital often flows rapidly back into high-quality companies, and market style undergoes sharp rotation.
5. Style Rotation Has Quietly Begun
It is worth noting that market style has already changed markedly. In addition to QMJ's 14.3% surge in July, the loss-making tech basket tracked by Goldman Sachs fell 11% in the third quarter; previously strong highly speculative stocks were hit hard—AST SpaceMobile (ASTS) fell 56%, and D-Wave Quantum (QBTS) fell 52%.
By contrast, high-quality consumer stocks rebounded markedly: since June 30, Procter & Gamble (PG) has risen 12.9%, Coca-Cola (KO) 17.3%, Church & Dwight (CHDN) 12.4%, and Colgate-Palmolive (CL) 6.2%, all outperforming the S&P 500's 2.3% over the same period.
6. How CFD Traders Should Respond
From a CFD trading perspective, this style rotation offers opportunities for two-way trading. As the market shifts from “chasing junk stocks” to “embracing quality stocks,” traders can capture the factor-rotation spread by going long quality-stock CFDs while shorting richly valued speculative-stock CFDs. However, it must be noted that CFDs involve leverage, so position sizing and stop-losses must be strictly controlled, and traders should be alert to the risk of amplified individual-stock volatility.
Historically, QMJ's two most significant monthly surges occurred in November 2000 and October 2008, respectively, and this historical comparison deserves caution. As the leadership rally in low-quality stocks reverses, tilting investment allocation toward high-quality, highly profitable companies may be the more prudent choice at present.
Want to capture opportunities from U.S. stock style rotation?
U.S. stock CFDs allow you to go long and short in both directions without holding physical shares, giving you flexible exposure to the style switch between quality stocks and speculative stocks. Go to Bitget CFD now to trade U.S. stock CFDs and seize this rotation opportunity as capital flows from the “junk-stock bubble” back into “quality assets.”
👉 Go to Bitget CFD now to trade U.S. stock CFDs
All trading education provided by Bitget is for educational purposes only and should not be considered financial advice. The strategies and examples shared are for reference only and may not reflect actual market conditions. CFD trading involves significant risk, including the potential loss of capital. Past performance does not guarantee future results. Please conduct thorough research and ensure that you understand the risks involved. Bitget is not responsible for any trading decisions made by users.


- 1. An Abnormal Reading Seen Only Once in 70 Years
- 2. What Exactly Does QMJ Measure?
- 3. The Turning Point After the Strongest Leadership Rally of Low-Quality Stocks in History
- 4. What History Tells Us
- 5. Style Rotation Has Quietly Begun
- 6. How CFD Traders Should Respond